


The third essay in our Breaking Bread series on rebuilding America’s defense industrial base.
From Precision to Scale
For decades, the American way of war was built around precision: see first, decide first, strike first. Satellites, sensors, stealth aircraft, precision-guided munitions, and networked command systems gave the United States a dominant edge and preserved its military superiority for a generation. Our adversaries had that same generation to study the playbook, and they used it, investing in hypersonics, drones, electronic warfare, cyber capabilities, and manufacturing at scale. All designed to degrade American precision, overwhelm it, or bypass it entirely.
Today’s conflicts demonstrate the problem. In Ukraine, small drones are central to surveillance, targeting, and strike operations. Electronic warfare reshapes which systems survive from week to week, adaptation cycles run in days, and cheap attritable systems proliferate. Commercial satellite imagery has become operational intelligence, and software updates matter as much as hardware upgrades. Future conflict may not look exactly like Ukraine, but the lesson is clear: precision and exquisite systems alone are not enough. Modern warfare now demands scale, resilience, and distribution across the battlefield.
In the war with Iran and across the Middle East, the United States experienced this firsthand as the new unit economics of the battlefield collided with the high end of the American arsenal. Layered air and missile defense held, but at enormous cost. Independent estimates suggest the United States absorbed up to $13 billion in base damage and equipment losses while expending $18.5 billion of air defense munitions[1] — largely to shoot down Iranian drones and missiles that cost a fraction to manufacture.
Countering this asymmetric threat requires more than replenishing the magazine quickly and cheaply. It requires a more distributed force architecture. Sensors, shooters, command nodes, and communications cannot be concentrated in a handful of platforms or fixed locations. They must be redundant and resilient enough to survive saturation, jamming, and attrition.
As Brig. Gen. Patrick M. Costello, Commanding General of the U.S. Army Fires Center of Excellence and Fort Sill, said of a key counter-UAS lesson from Operation Epic Fury:
“I will never co-locate a sensor and a shooter again. Ever. It’s just bad business.”[2]
None of this retires the legacy force. America remains exceptional at designing advanced military systems. Carriers, strike aircraft, satellites, and missile defense still anchor American power, but modern conflict increasingly rewards speed, software iteration, distributed architecture, and systems cheap enough to lose and fast enough to replace. Precision still matters. Now the equation is precision plus autonomy plus scale, distributed across the battlefield.
Autonomous, Distributed Mass
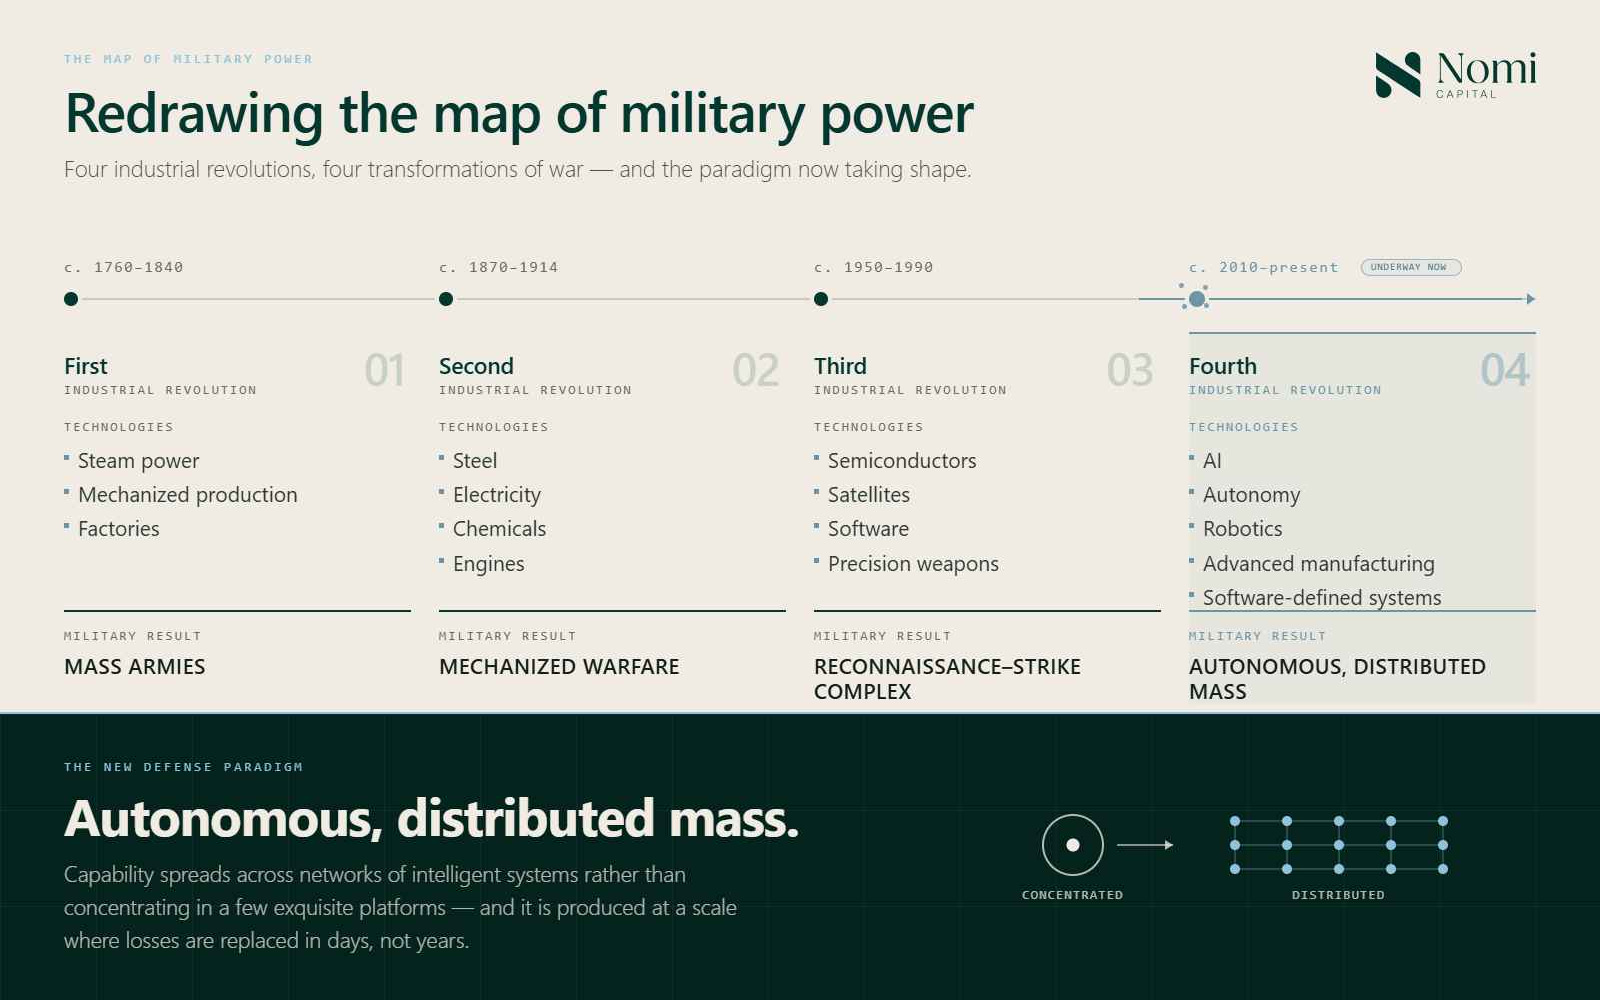
This is where the Fourth Industrial Revolution collides with the next leap in military doctrine. AI, autonomy, robotics, advanced manufacturing, and software-defined systems are changing not only what militaries can build, but how fast they can build it.
Together, these forces are producing a new defense paradigm: autonomous, distributed mass. Capability spreads across networks of intelligent systems rather than concentrating on a few exquisite platforms, and those systems are produced at a scale where losses are replaced in days rather than years. When one node is jammed, degraded, or destroyed, the network adapts, because survivability comes from distribution, redundancy, and replacement rate as much as from stealth or armor.
The next generation of military advantage will belong to countries that can manufacture intelligent systems at scale, distribute capability across the battlefield, and replace losses faster than adversaries can impose them. America’s defense industrial base, still one of the great strategic assets in the world, is not yet built to deliver that future at the speed or scale required. This essay is about that gap, and about the companies closing it.
The Industrial Base Was Built for a Different Era
Before Russia invaded Ukraine, the United States produced roughly 15,000 155mm artillery rounds a month, about two days of Ukraine’s peak expenditure[3]. The war with Iran exposed the same gap at the top of the arsenal. This time the issue was not the cost of each intercept but the depth of the magazine itself: more than 1,000 Tomahawk cruise missiles fired, close to half the Patriot interceptor stockpile spent, more than half of the THAAD inventory drawn down. Independent analysts put the return to pre-war Patriot and THAAD levels around 2029, and cruise-missile stocks around 2031[4].
And Iran was the limited case. Wargame after wargame finds the United States burning through its critical munitions within the first weeks of a high-intensity fight over Taiwan, while the lines meant to replace them still measure output in years. The consequence is already clear: the United States is triaging its allies, delaying weapons deliveries to some partners while fast-tracking others, because it cannot arm them all at once. The constraint is no longer budget or political will; it is capacity.
The shortfall is structural. After the Cold War, defense spending fell and the industry consolidated, narrowing a broad ecosystem of industrial companies, technology firms, and defense suppliers into a small group of large primes. Consolidation created scale, but it also reduced competition, and the system left behind moves at the pace of legacy procurement: development cycles too long, costs too high, supply chains too brittle, software cadence too slow, manufacturing capacity too limited.
Software Eats the Battlefield, But Manufacturing Wins the War
Investors spent a decade repeating the mantra that software is eating the world. In defense, that is only half true. Autonomy still needs airframes and munitions, AI still needs compute and power, and distributed systems still need factories, supply chains, and workers who can build them. Advanced manufacturing is not a support function. It is a defense technology.
The companies built for this era blend software, hardware, and manufacturing into a single operating model: vertically integrated where it matters, software-defined at the core, manufacturing-aware from day one. We have backed several of them.
Anduril proved the model, growing from a startup into a defense prime in under a decade.
Firehawk is rebuilding the magazine, using additive manufacturing to 3D-print solid rocket motors and compress production from weeks to days.
Castelion is modernizing America’s strike arsenal, developing hypersonic weapons at industrial rate and commercial cost, on timelines measured in months rather than decades.
Armada is building the compute, a vertically integrated edge platform that runs AI in the air-gapped, remote, and contested environments where hyperscale cloud cannot go.
The New Arsenal
The original arsenal of democracy was measured in factories, shipyards, steel, aircraft, and munitions. Its successor spans a wider map: autonomous aircraft and unmanned vessels; counter-drone systems, directed energy, and electronic warfare; edge AI infrastructure, resilient communications, and secure data networks; nuclear power, advanced manufacturing, industrial AI, and new supply chains for critical materials.
It also reaches into domains the old arsenal never had to hold. Orbit has shifted from a permissive environment to a contested one, and the satellites that underpin critical commercial and defense capabilities are under growing threat. Starfish Space is building the logistics layer to change that, with autonomous servicing vehicles that can dock with, reposition, and de-orbit satellites to keep American orbital assets in the fight.
Energy is another new domain. AI and autonomy both run into a constraint harder than code: power. Hyperscale compute and the military’s push for resilient, off-grid energy converge on the same bottleneck of fuel, and Standard Nuclear is securing the domestic supply chain for the advanced fuel next-generation reactors require, producing TRISO-based HALEU at a time when the United States still depends heavily on foreign sources for enrichment.
Defense, AI, energy, manufacturing, space, and infrastructure are blurring into a single industrial build-out. Even Anduril, the proof case everyone cites, is on pace for roughly $4.3B[5] in revenue this year against a trillion-dollar defense budget: less than half a percent. That lack of penetration is the opportunity.
The Messy Middle
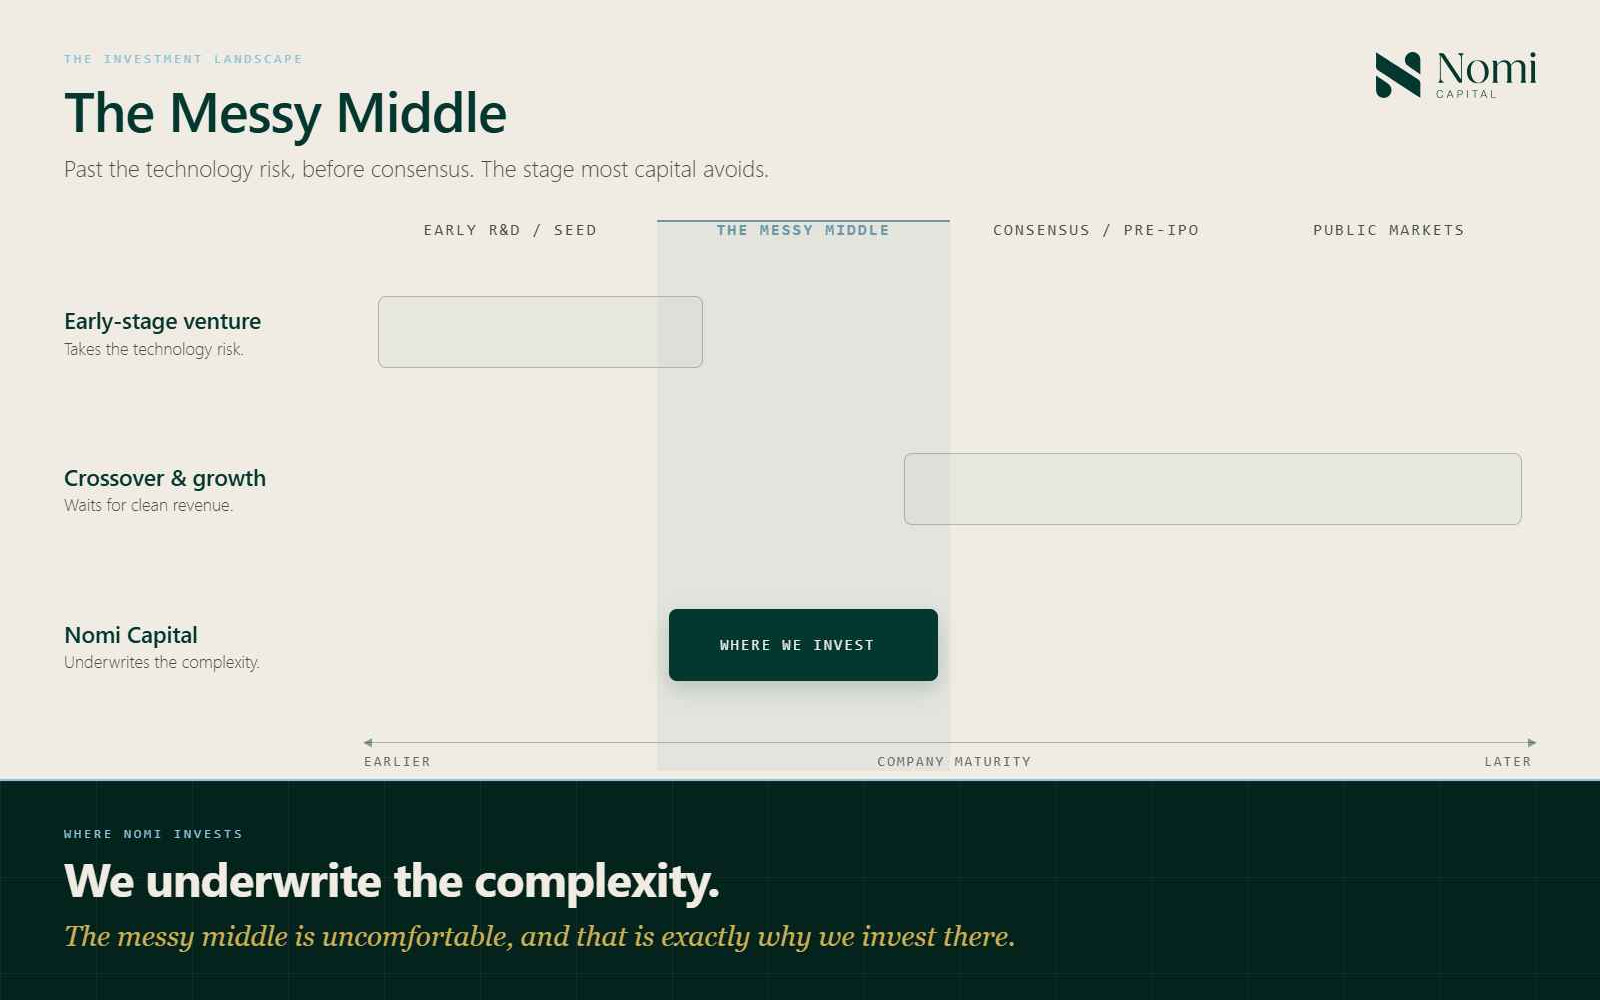
The messy middle is the stage after early R&D but before the winners are obvious. The product works, customer urgency is real, and there may already be pilots, contracts, deployments, or early production. What is missing is everything that later makes a company look safe: a settled procurement path, clean financials, broad institutional sponsorship.
So most capital sits this stage out. Early-stage venture has already taken the pure technology risk, crossover investors are waiting for cleaner revenue and an obvious IPO trajectory, and generalists struggle to underwrite procurement, customer concentration, government budgets, and classified programs. By the time everyone agrees, the best entry points are gone.
This is where Nomi invests. We earn our way into these companies through a network that runs across the operators building them, the government customers fielding them, and the capital partners scaling them.
Why This Moment Matters
None of this will be easy. Procurement is still slow, budgets are still complex, manufacturing is unforgiving, and many promising companies will fail. But the prize is bigger than defense. The companies that win will build factories, create skilled jobs, and move technology between military and commercial markets. The countries that dominate the decades ahead will be those that harness this Fourth Industrial Revolution across both their arsenals and their economies.
The Breaking Bread series began with a simple argument: rebuilding the defense industrial base takes a coalition, because government cannot do it alone and neither can the legacy primes, the startups, or private capital. Three essays in, that coalition is forming. Washington is working with nontraditional vendors, engineers who once built consumer apps and cloud infrastructure are turning toward national security, allied demand is rising, and private capital is flowing back into the physical world.
The new arsenal of democracy is being built now. We are backing the builders who will define it.
[1] M. Cancian and C. Park, The War May Be Ending. What Did Epic Fury Cost?, CSIS, 23 June 2026.
[2] Brig. Gen. P. Costello, remarks at the 2026 Fires Symposium, video excerpt posted to Vimeo, at approximately 30:50, accessed 5 July 2026, https://vimeo.com/showcase/12205814?video=1183847029.
[3] S. Erlanger and L. Jakes, U.S. and NATO Scramble to Arm Ukraine and Refill Their Own Arsenals, The New York Times, 26 November 2022.
[4] M. Cancian and C. Park, Rebuilding U.S. Missile Inventory: A Multiyear Project, CSIS, 27 May 2026.
[5] C. Weinberg, Anduril Forecasts More Than $4 Billion in Sales, $1 Billion in Losses, The Information, 5 March 2026.